Exact2Pass

The modern Canadian retail wealth management, retail banking, and mutual fund advisory landscape demands rigorous regulatory compliance, deep knowledge of capital market instruments, and robust client discovery protocols. As Canadian financial institutions adapt to evolving Client Focused Reforms (CFR), stringent Know Your Client (KYC) requirements, and heightened regulatory scrutiny from the Canadian Investment Regulatory Organization (CIRO) and provincial securities commissions, dealing representatives must master the end-to-end investment advisory workflow. Achieving the Canadian Securities Institute Investment Funds in Canada (IFC) credential—often taken alongside or as an alternative to the Canadian Investment Funds Course (CIFC)—validates your technical ability to evaluate mutual fund performance, construct risk-appropriate portfolios, assess investor behavioral biases, and enforce statutory suitability guidelines. However, many aspiring personal banking advisors, financial planners, and investment representatives struggle on this intensive proctored examination because they treat it as a passive vocabulary exercise. Relying on flat answer keys or context-stripped question files found on unverified public forums cannot prepare you for the complex situational logic of calculating total fund management expense ratios (MER), determining taxable capital gains across registered versus non-registered accounts, or resolving ethical conflicts under the MFDA and CIRO code of conduct rules.
True success on this 18-chapter, 100-question multiple-choice assessment requires a comprehensive, multi-dimensional grasp of macroeconomics, financial statement analysis, fixed-income pricing dynamics, and alternative managed products. Advisory candidates must demonstrate sharp diagnostic judgment when comparing open-end mutual funds with exchange-traded funds (ETFs), closed-end funds, segregated funds, and principal-protected notes (PPNs). Candidates frequently spend several months searching for high-yield ifc exam questions online, hoping to locate an updated investment funds in canada ifc study guide to measure their readiness, or reviewing mutual fund prospectus documents to evaluate sales charges and redemption fees. Without interactive workspace environments, a structured wealth management course, or targeted practical practice that can provide actual help in exam preparation, passive reading fails to build the diagnostic capabilities needed to handle portfolio rebalancing calculations or isolate suitability errors during account opening procedures.
At Exact2Pass, we replace passive reading with active, scenario-driven structural exercises designed to build true professional confidence. Our premium preparation workspace simulates the functional operational layers, portfolio allocation models, and regulatory compliance scenarios of the active Canadian wealth management sector. We guide you through executing gap analyses on client financial profiles, evaluating mutual fund management styles (active vs. passive, top-down vs. bottom-up), calculating risk-adjusted returns using Sharpe ratios and quartile rankings, and applying proper tax-deferral strategies within RRSPs, TFSAs, and FHSAs. This focused practice builds the exact client discovery judgment and compliance execution skills demanded by leading Canadian financial institutions, ensuring you pass your official CSI proctored evaluation on your very first attempt.
The IFC certification exam is engineered to evaluate your end-to-end mutual fund advisory, portfolio management, and regulatory compliance capabilities across modern Canadian financial service environments. Our realistic simulation platform replicates active financial planning dashboards, mutual fund comparison matrices, and real-time KYC validation interfaces instead of serving up generic multiple-choice questionnaires. You will master the underlying capital market operations, investor behavioral profiles, and statutory compliance frameworks of the active Canadian financial system, preparing you to tackle any scenario-based advisory question with ease.
What is often a requirement of maintaining licensing as a mutual fund sales representative?
What financial instrument is used for publicly-funded capital projects?
The demand for blue widgets increases sharply due to a newspaper report that using blue widgets improves recovery from influenza. What can be said about the law of supply?
Over the course of a couple of weeks and several appointments, Harold was finally able to provide an investment solution for his new client, Felicia. It was a lump sum investment where they plan to see her
money grow for the next 5 years.
With regards to Know Your Client (KYC) requirements, what are Harold ' s responsibilities moving forward?
You have been researching Canadian equity mutual funds for a new client. You come across the following information.
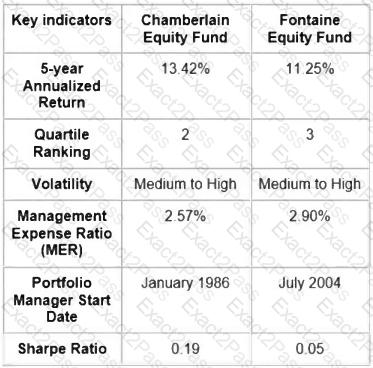
What can you conclude from this information?
Francis wants to redeem his US Asset Allocation Fund as he needs the money for a down payment for a home purchase. The current proceeds from the redemption are USD $27,859, and the current CAD/USD exchange rate is 0.7353.
How much will Francis receive in Canadian dollars when he redeems the Funds? Please round your answer to the nearest dollar.
An unlicensed person was hired at a securities administrator, and they accepted their first case, which may result in suspending a registrant ' s license. The new hire immediately requests a subpoena of witnesses (and evidence) and requests guidance from the FATF. What error did the new hire likely commit?
In a mutual fund sales representative ' s interaction with clients, what term best describes a set of moral principles that incorporate both the letter of the law and the spirit of the law?
The following information is available for Monique:
Number of children
1
Lifetime RESP contributions to date
$45,000
CESG received to date
$7,200
Family income
$120,000
Desired current year contribution
$7,000
What is the maximum RESP contribution that Monique can make this year?
What is a characteristic of financial statement trend analysis?
Your soon-to-be-retired client has accumulated $700,000 in a mutual fund investment. He has consulted with you with respect to systematic withdrawal plans. His other sources of income in retirement are uncertain. He is not interested in leaving a legacy at his death. Which plan would best suit his needs?
What is a mutual fund sales representative ' s legal responsibility when dealing with clients?
Khuyen is a Dealing Representative for Stark Contrast Investments. Her dealer has relationships with 20 different mutual fund families. This gave her the flexibility to sell two different types of funds from two
different fund families to her client, Bao. $5,000 was invested in the Blue Moon Global Balanced fund and an additional $5,000 was invested in the Orange Sun Asset Allocation fund. Khuyen has been
reviewing the performance of both funds and has determined that Bao would be better off being fully invested in the Blue Moon Global Balance fund. Bao had previously signed a Limited Authorization Form
(LAF) for Khuyen, so she goes ahead and does not worry about consulting with Bao before making the change.
What type of activity has Khuyen performed?
At 4:00 p.m. Eastern Time on July 6, the following information is collected for the Marigold Canadian Dividend Fund:
What is the net asset value per unit NAVPU for the Marigold Canadian Dividend Fund for July 6?
Which of the following statement about Exchange Traded Funds (ETFs) is TRUE?

